Defining Group Health Plans: Key issues
Update for 2018 - In December 2016 the IRS issued guidance for the Qualified Small Employer HRA Plan for groups with 50 or fewer full time employees to reimburse non-group premium...
$99 one-time fee in PDF via email*
$149 one-time fee in PDF email* + Deluxe Binder
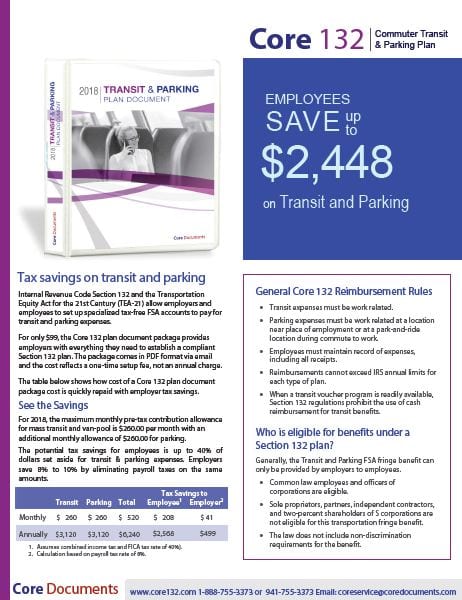
Section 132 of the tax code provides that employers may set up a flexible spending account benefit for employees to pay work-related transit and parking expenses with tax-free dollars. Tax savings on employee contributions to these FSAs come from income and FICA taxes for employees, with matching payroll tax savings for employers. All employers need to get started is a written plan document

In 2026, employees may set aside up to $340 monthly for eligible transportation costs necessary to get to work and a separate $340 monthly for eligible parking expenses paid so that the employee may be at work. Note that these amounts are contributed separately and held separately; transfers from parking to transportation or vice versa are not allowed.
Total tax savings depends on the amount an employee sets aside via pre-tax salary deductions and the employees tax bracket. For example:
| Income Tax Bracket | Income Tax Savings | FICA Tax Savings | Annual Tax Savings |
| 22% | $1,584.00 | $550.80 | $2,134.80 |
| 32% | $2,304.00 | $550.82 | $2,854.82 |
| 37% | $2,664.00 | $550.82 | $3,214.82 |
| Table assumes employee contributes the combined maximum monthly allowance of $600 ($300 parking and $300 transportation)for a yearly total of $7,200. FICA (Social Security and Medicare) tax rate is 7.65%. | |||
Unlike other FSAs, a Section 132 transit and parking FSA has no use-it-or-lose-it provision. If the employee does not use the full amount before the end of the program year, the left over amount is carried forward to the next year.
As a general rule, the Transit and Parking FSA fringe benefit can only be provided by employers to employees. Common law employees and officers of corporations are eligible; however, sole proprietors, partners, independent contractors, and two-percent shareholders of S corporations are not.
The law does not include non-discrimination requirements for the benefit.
Parking expenses that can be paid with pre-tax dollars in a Section 132 plan include the cost of:
Qualified amounts include costs of any pass, token, fare card, voucher, or other item that entitles the employee to use mass transit for the purpose of traveling to or from their place of work.
However, when a transit voucher program is readily available, Federal regulations prohibit the use of cash reimbursement as a way to provide transit benefits.
The mass transit can be a public system, or a private enterprise provided by a company/individual who is in the business of transporting people in a “commuter highway vehicle,”defined in part as:
Commuter highway vehicles may be owned or leased by an employer to be used by employees or a third-party provider for transportation purposes. Employees can also own and operate commuter highway vehicles.
The Commuter Transit and Parking Plan Document Package Includes:
Summary of Plan Sponsor Responsibilities, Resolution to Adopt, Plan Document, Employee Summary Plan Description (SPD), Election Forms, Claim Form, Change Form and Complete Administration Guide.
$149 one-time fee in PDF via email*
$199 one-time fee in PDF email* + Deluxe Binder
No annual fee — Core Documents does not require an annual renewal fee to maintain your plan document package. A plan document only needs to be updated when there are changes in the plan or in the law that make it necessary. We will notify you when there are sufficient changes in the Code to require amending and restating your Plan and ask that you keep us informed when there is a change to your plan. You can amend and update your plan document anytime, at a discounted fee and only when necessary, which is the most cost-effective way to maintain it.
Fast Service — Most orders placed by 3 PM are returned via email the same day, Monday through Friday. Weekend orders are sent out Monday morning. Plan document packages are processed in the order received. During our busiest months (December, January, and February), the rush order fee (see order form) marks your document to be processed immediately.
Refund Policy: Goods and services provided by Core Documents, Inc. are non-refundable upon receipt. Orders cancelled prior to shipping are subject to a fee to cover the cost of goods and services provided during the review, draft, and preparation of your order.
Core Documents is the country’s leading provider of cost-effective, tax-saving benefit plan documents for Section 125 Cafeteria plans and Health Reimbursement Arrangements. The Trusted Source since 1997, thousands of satisfied agents and employer groups nationwide rely upon Core Documents for free plan design consulting services, plan document updates, ERISA Wrap SPDs, and administration services.
Update for 2018 - In December 2016 the IRS issued guidance for the Qualified Small Employer HRA Plan for groups with 50 or fewer full time employees to reimburse non-group premium...
IRS.gov: Form W-2 Reporting of Employer-Sponsored Health Coverage The Affordable Care Act requires employers to report the cost of coverage under an employer-sponsored group...
No more blogs
Cut through all the rhetoric and speak directly to an IRS Section 125 Plan expert Certified In Flexible Compensation.
P.O.Box 14538, Bradenton, FL 34280 Office: 501 Village Green Parkway, Suite 11, Bradenton, FL 34209
Copyright 2004-2026 Core Documents, Inc., All rights reserved. Privacy & Refund Statements